
Contents
Mortgage rates: should you wait? Many homebuyers ask this question before making an offer. After all, rates directly influence monthly payments and total borrowing costs.
However, waiting does not guarantee a better financial outcome. Home prices, available inventory, personal savings, and loan terms also shape affordability. Therefore, buyers should examine the complete picture before delaying a purchase.
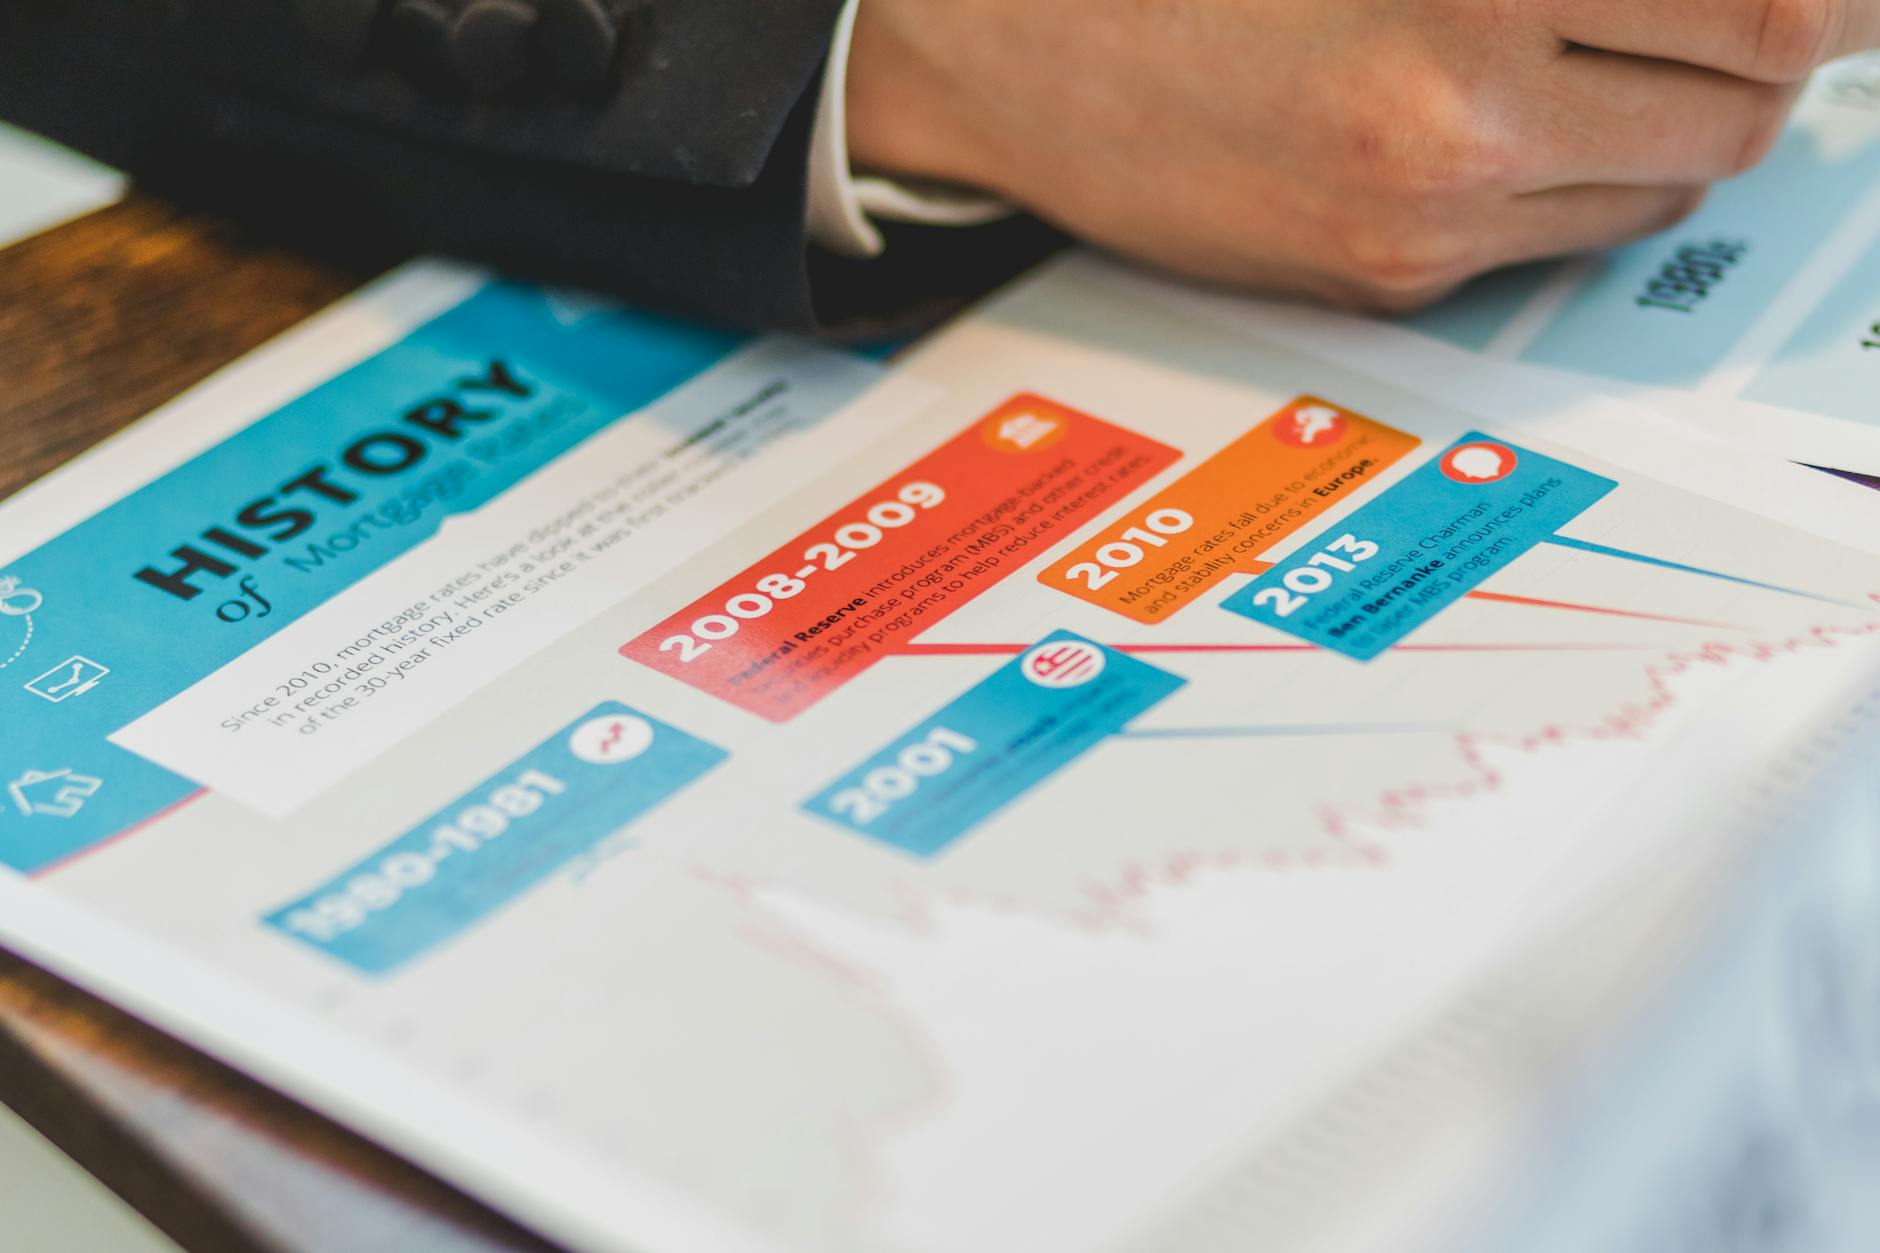
This guide explains how to evaluate rates, personal readiness, market conditions, and refinancing possibilities. Moreover, it offers practical steps for making a confident decision in 2026.
Mortgage rates: should you wait for a lower rate?
Predicting short-term mortgage movements remains difficult. Rates respond to inflation, employment, bond markets, economic growth, and central bank policy. Consequently, even experienced analysts cannot guarantee the next significant change.
A lower future rate could reduce your payment. However, home prices might rise while you wait. Furthermore, stronger buyer demand could create more competition for desirable properties.
Instead of chasing a perfect rate, identify an affordable payment range. Then compare homes and financing options within that limit. This approach supports a decision based on facts rather than speculation.
How mortgage rates affect your real costs
A mortgage rate determines part of your monthly principal and interest payment. Therefore, a higher rate usually reduces your purchasing power. It also increases interest costs when other loan details remain unchanged.
However, the advertised rate tells only part of the story. Buyers should also review annual percentage rates, lender fees, discount points, and closing costs. In addition, loan duration can substantially change total interest expenses.
Request written loan estimates from several lenders. Next, compare equivalent loan types and lock periods. For additional consumer guidance, visit the Consumer Financial Protection Bureau homebuying resource.
UpCardsCredit card comparatorPick 2 cards and see, line by line, what changes between them.Use it →Compare more than the monthly payment
A manageable payment matters, but ownership includes other expenses. For example, property taxes, insurance, maintenance, utilities, and association fees can affect your budget.
Therefore, calculate a complete monthly housing estimate. Additionally, keep emergency savings after paying the down payment and closing costs. A depleted savings account can make routine repairs financially stressful.
You should also review adjustable-rate and fixed-rate mortgages carefully. Fixed rates offer predictable principal and interest payments. Conversely, adjustable rates can change after an initial period.
Mortgage rates: should you wait based on your finances?
Your financial readiness deserves more attention than daily rate headlines. First, review your income stability, existing debts, credit profile, savings, and future plans. These factors determine whether homeownership fits your situation.
A stronger credit profile may improve your available loan terms. Therefore, check your credit reports before applying. Correct valid errors, reduce expensive debt, and avoid opening unnecessary accounts during the application process.
Moreover, consider how long you expect to remain in the home. Buying creates transaction costs, while selling creates additional expenses. Consequently, a short ownership period can weaken the financial case for purchasing.
Signs that buying now may make sense
Buying now may work when the payment remains comfortable without optimistic assumptions. Furthermore, the property should meet your needs for several years.
Use conservative estimates for maintenance and insurance. Also, preserve enough cash for emergencies and moving expenses. A lender’s approval amount should not replace your personal spending limit.
• You have stable income and dependable emergency savings.
• You can afford the complete housing payment.
• You plan to stay long enough to justify transaction costs.
• You found a suitable property at a reasonable price.
• You understand the loan’s fees, terms, and risks.
Mortgage rates: should you wait when prices are rising?
Rates and prices can move in different directions. Therefore, waiting for cheaper financing may expose you to higher property prices. Local inventory can also decline during that period.
On the other hand, some markets offer buyers more negotiating power. Sellers may accept price reductions, repair credits, or closing-cost assistance. Thus, local conditions matter more than broad national headlines.
Ask a qualified local agent for recent comparable sales and inventory trends. However, review the evidence independently. You can also learn more here about planning major financial decisions.
Consider the cost of waiting
Waiting has potential benefits and costs. For instance, you might save a larger down payment or improve your credit. Additionally, you could gain time to understand preferred neighborhoods.
However, you may continue paying rent during that period. Prices could also increase, while suitable homes become harder to find. Therefore, compare realistic scenarios rather than assuming rates will fall.
Create three projections using current, moderately lower, and moderately higher rates. Then include estimated prices, taxes, insurance, and savings. This exercise clarifies which changes could alter your decision.
Build a flexible mortgage strategy
A flexible strategy can reduce pressure around timing. Start by comparing multiple lenders, loan programs, fees, and rate-lock options. Moreover, ask each lender to explain every cost clearly.
You can also negotiate seller concessions where local conditions allow them. In some cases, concessions may support closing costs or a temporary rate buydown. However, compare that benefit against a lower purchase price.
Finally, discuss refinancing carefully rather than treating it as guaranteed. Future rates may not fall enough to justify refinancing costs. Therefore, your original mortgage should remain affordable without future changes.
• Set a firm monthly housing limit.
• Compare at least several lender offers.
• Review rates, points, fees, and annual percentage rates.
• Ask about lock terms and extension costs.
• Keep cash reserves after closing.
Frequently Asked Questions
Will mortgage rates definitely fall in 2026?
No one can guarantee that outcome. Rates react to changing economic conditions and financial markets. Therefore, build your plan around today’s affordable options.
Should I buy now and refinance later?
That strategy can work, but refinancing never comes guaranteed. Moreover, refinancing involves eligibility rules, fees, and market conditions. Buy only when the current payment fits comfortably.
How can I get a better mortgage offer?
Strengthen your credit, lower costly debt, and compare several lenders. Additionally, review loan estimates carefully. Negotiate fees and points when possible.
Conclusion
Mortgage rates: should you wait? The answer depends on affordability, financial readiness, local prices, and personal goals. A future rate drop alone should not control your decision.
Therefore, compare complete loan costs and test several realistic scenarios. Most importantly, choose a payment that protects your savings and everyday budget. A disciplined plan offers more value than perfect market timing.


